

The 3 Best Stocks to Buy in the Next 60 Days

We are 4 years into a bull market, and by now nearly every stock worth talking about is sitting at or near its all-time high. So pointing at past gains does not help you much. What helps you is knowing which companies have a real reason to keep climbing, right now.
So today we are giving you 3 stocks we're going to watch over the next 60 days. Each one has a specific, dated catalyst landing inside the next 2 months, the kind of moment that can move shares in a hurry. 2 of them report earnings within days. Another heads into the single biggest selling season of its year.
A note from our sponsors...
The ONLY AI opportunity you should be looking at
This is the ONLY AI wealth-building opportunity you should be watching right now.
No. It's not about Nvidia, Tesla, or Meta...
It's about one overlooked company profiting off AI "digital goldmines" that are poised to experience 100x growth very soon.
This new opportunity will change the market and make investors a lot of money.
That's why it has received a $500 billion commitment from President Trump himself...
Learn more about this little-known company here >>>
SanDisk (SNDK)
We're going to start the list off with SanDisk (SNDK).
Artificial intelligence is devouring storage. Every model that gets trained, every answer that gets served, all of it pulls from mountains of flash memory, and SanDisk is a pure play on that wave. Every new AI data center going up needs enormous amounts of this storage, and that demand shows no signs of slowing. The timing is what makes this urgent, SanDisk reports earnings on October 29th, just days from now.
And this is a company that has been crushing the number. We are talking 6 straight earnings beats, and not by pennies.
This explains why Wall Street experts see the party continuing. They forecast revenue growing nearly 45% a year, and that is translating into earnings growth of almost 48% a year in the year ahead, running well ahead of both its industry and the broader market.
Now, SNDK's rally since it went public in February was jaw-dropping, but the share price has pulled back by more than 20% in the last 30 days. It's actually more than 40% off of its 52-week high. That's what makes this a compelling play right now.
Because right now, shares trade at a forward P/E of just 8.
And the PEG ratio, which is simply the P/E adjusted for growth, comes in at just 0.37. Remember, the average stock trades around 1.5, roughly 4 times higher. Meaning SanDisk shares could quadruple from here and still be cheaper than the average company. Growth is nice. But growth plus value, that is much, much nicer. And management is buying back shares hand over fist, a strong vote of confidence.
Wall Street is pounding the table too. 16 analysts cover shares and they land on a consensus Strong Buy recommendation, with 10 of them at a Strong Buy recommendation outright. The average price target implies an upside of more than 65%. There are plenty of top 1% or top 2% ranked analysts on the panel, and they're the most bullish ones, with fair value targets that see more than 100% upside in the cards. Exactly what you want to see.
Now let's pop the hood on our Zen Ratings quant model. It analyzes every stock across 115 different fundamental, technical, and AI factors, boils it down to an intuitive letter grade from A through F, and then breaks out 7 Component Grades, Value, Growth, Momentum, and more, to show each stock's unique strengths and weaknesses.
SanDisk earns an A rating, a Strong Buy recommendation, putting it in the top 1% of all stocks. Let's walk the Component Grades up. Momentum lands in the top 19%, pointing to timely shares. Sentiment, the Smart Money crowd moving in, top 8%. Value, based on 21 different value measures, top 4%. Growth, which foreshadows more earnings beats ahead, top 5%. And the standout, Financial strength, top 1%, operational excellence that shows up time and again in future earnings reports. Growth and Financial strength are the 2 most vital grades for predicting future outperformance, and SanDisk has both near the very top. Plus, it is the number 1 ranked stock out of 32 in all of the Computer Hardware industry, topping names like Dell and Seagate. The one soft spot is Safety, which grades a D, in the bottom 11% of the market, a reminder that this is a high-octane ride.
But with the AI build-out still accelerating into that October 29th report, the setup is about as timely as they come. That makes SanDisk a powerful way to start our list. But our next pick could not be more different, a household name the market gave up on…
Target (TGT)
Our second pick is a genuine turnaround in Target (TGT).
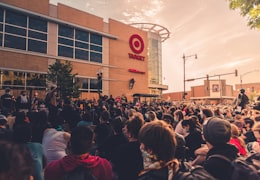
You know Target. The big red bullseye. And a few years back, shares fell apart, collapsing from over $250 down into the low $80s as sales sputtered. The market basically left it for dead. But something has changed, and here is why it is worth your attention right now.
Under a new CEO, the turnaround is actually working. The new leadership is cleaning up the merchandising and leaning back into the exclusive brands shoppers come to Target for. The proof is in the numbers, Target has delivered 5 straight earnings beats, with its most recent quarter sailing past estimates and management raising guidance. The earnings recovery is picking up steam.
And the catalyst is right on the calendar. Target reports on November 18th, and that is no ordinary quarter. That report covers the run into the holidays, the single most important stretch of the entire year for a retailer, with management's read on holiday demand attached to it. And here is why that makes it a 60-day story. A strong holiday read, with guidance to match, is just the kind of catalyst that can get a stock like this moving again. And a strong Black Friday showing is exactly the kind of headline that gets a sleepy name like this back on the radar.
Here is the kicker. Even with the turnaround underway, shares still trade for around 16 times forward earnings, while for Walmart and Costco, that number is closer to 40. That is a lot of value heading into its strongest season.
And the top ranked analysts are coming back around. One of them, ranked in the top 4% of all Wall Street analysts for stock picking, has a Strong Buy recommendation on Target, with a fair value target that, as of this writing, implies better than 20% upside in the year ahead. And just weeks ago, another firm upgraded shares to a fresh Street high.
Now let's appreciate the outlook from our Zen Ratings model. We're looking at another elite stock, with a Zen Rating of A, so equivalent to a Strong Buy recommendation. Overall fundamentals put it in the top 1% of everything we track. And this is one of those rare cases where almost everything grades well, so let's run them quickly. Value top 14%, Growth top 13%, Momentum top 12%, Financial strength top 9%, the AI factor top 6%, and that measures likely future timeliness of shares, not how much AI the company sells. And the standout, Sentiment, also top 6%. That is the Smart Money piling back into a name everyone else wrote off. Our model even ranks Target the number 1 stock in the entire Discount Store group, ahead of tickers like Dollar General and Dollar Tree. The one soft spot is Safety, which grades a D, in the bottom 11% of the market, so expect some bumps along the way.
One risk heading into that November print is that Target is still early in its turnaround, so if holiday shoppers tighten their belts, the quarter could come in soft. But a beaten down household name, 5 straight beats, top ranked analysts upgrading, and a top 1% rating heading into the biggest quarter of its year, that is a turnaround worth owning before the crowd fully believes it.
Keep that one in mind. Because the last stock is the one we think most of you have never heard of, and that is exactly the opportunity.
If you want to stay one step ahead of the market, join our Live training every Monday, where we share an updated market outlook and trading plan to outperform, plus a Trade of the Week based on our proven Zen Ratings quant model. It's a free event, but you do need to register at wallstreetzen.com/live. And even if you can't join live, it's still worth signing up, since a replay goes out to all registrants to watch whenever is convenient.
Omnicell (OMCL)
Here is something you do not see very often. A company that our model rates in the top 2% of the entire market, that you can buy today for more than 30% below its 52-week high.
Let's back up. The company is Omnicell (OMCL). And what they do runs quietly inside the walls of thousands of hospitals, the automated systems that store, track, and dispense medication so the right patient gets the right drug at the right dose.
Here is why it is exciting now. Hospitals are fighting a brutal, ongoing shortage of pharmacy staff, and Omnicell's automation is how they cope, which means sticky, recurring revenue that keeps compounding. Think about it. A hospital cannot afford a medication error, and it cannot afford to run short on staff. Omnicell answers both at once. Once a hospital wires Omnicell into its pharmacy, it does not rip it back out. That is the kind of durable, recurring revenue our model loves to see. And that installed base keeps throwing off software and service revenue long after the hardware ships.
And the market has handed us a gift. Shares have pulled back hard, and we can now snag them well off those highs. This is a classic Buy the Dip, because the business underneath is firing.
Here's what caught our eye. Going back 3 years, Omnicell has missed Wall Street's number exactly once. And since that lone miss, it beat big, then doubled the estimate the very next quarter.
This explains why Wall Street experts see even modest revenue growth translating into earnings growth of nearly 40% a year going forward, more than double the pace of its industry peers in the year ahead. And just like our first pick, the catalyst is imminent. Omnicell reports earnings on October 29th. And a beat that day could be the spark that snaps this dip shut.
The value here is just as compelling. According to a discounted cash flow model, shares trade a full 34% below the fair value estimate of around $54.
And the PEG ratio sits near 1.07, which makes this a GARP stock, Growth At A Reasonable Price, still below that 1.5 average for the market.
Now, Wall Street coverage is thin. Just 3 analysts are rating shares. Gladly, all 3 are firmly on board with Strong Buy recommendations, and the best-ranked of them, in the top 26%, sees fair value implying, as of this writing, roughly 40% upside in the year ahead. With coverage this light, each new analyst coming onboard is one more catalyst to push shares higher, it pays to be early.
And under the microscope of our Zen Ratings model, Omnicell earns that coveted A rating, a Strong Buy recommendation, in the top 2% of all stocks. In fact, it is the number 1 ranked stock out of 42 in its entire Health Information Services group. Let's walk the grades up. Financial strength grades in the top 22%, still well above the pack. Safety, top 10%. Growth, which points to more earnings beats ahead, also top 10%. Value, based on 21 different measures, top 9%. And the standout, Sentiment, top 7%, the Smart Money crowd moving in with conviction. The one soft spot is Momentum, which grades a C, in the bottom 30% of the market, which is just what you would expect from a stock that has pulled back.
The biggest negative for Omnicell is that it leans on hospital budgets, if health systems pull back on new automation, sales can slow. But put it together, the Smart Money leaning into a healthy, cheap, growing company while shares have slipped, with the labor shortage still squeezing hospitals into that October 29th report. That demand isn't going anywhere. And that is why we saved Omnicell for last.
So there you have it, 3 stocks for the next 60 days. SanDisk, riding the AI memory wave into earnings. Target, a household name turnaround heading into its biggest quarter. And Omnicell, a quiet dip in a beaten-down winner that most of the market has not found yet. And that is the thread tying them together, 3 top rated companies, each with a real catalyst inside the next 60 days.
And remember, 2 of these report within days, so if any of them caught your eye, you will want to do your homework before then.
You can pull a free rating on over 4,600 stocks yourself just by typing in a ticker at wallstreetzen.com. So be sure to bookmark the site.
What to Do Next?
Want to get in touch? Email us at news@wallstreetzen.com.
Keep Reading
See All News



Company
AboutNewsBlogStock Investing FAQPlansPrivacy PolicyTerms of ServiceCancellation & RefundsPerformanceHelp GuidesContactTwitterYouTubeNewsletterInformation is provided 'as-is' and solely for informational purposes and is not advice. WallStreetZen does not bear any responsibility for any losses or damage that may occur as a result of reliance on this data.