

4 Stocks to Buy Heavy in November 2026
After four years of a powerful bull market, it can feel like all the easy money has already been made.
But something interesting is happening beneath the surface. Market gains, once heavily concentrated in a handful of mega-cap technology companies, are beginning to broaden into other corners of the economy.
A note from our sponsors...
Could a $100 Options Trade Become $1,000+?
It's possible, and this new report shows you how traders approach it. Inside, you'll discover a simple system for spotting low-priced options trades with outsized gain potential. You'll learn the core vocabulary, how calls and puts work, the risk factors to weigh before every trade, and practical examples to follow. Download the report now.
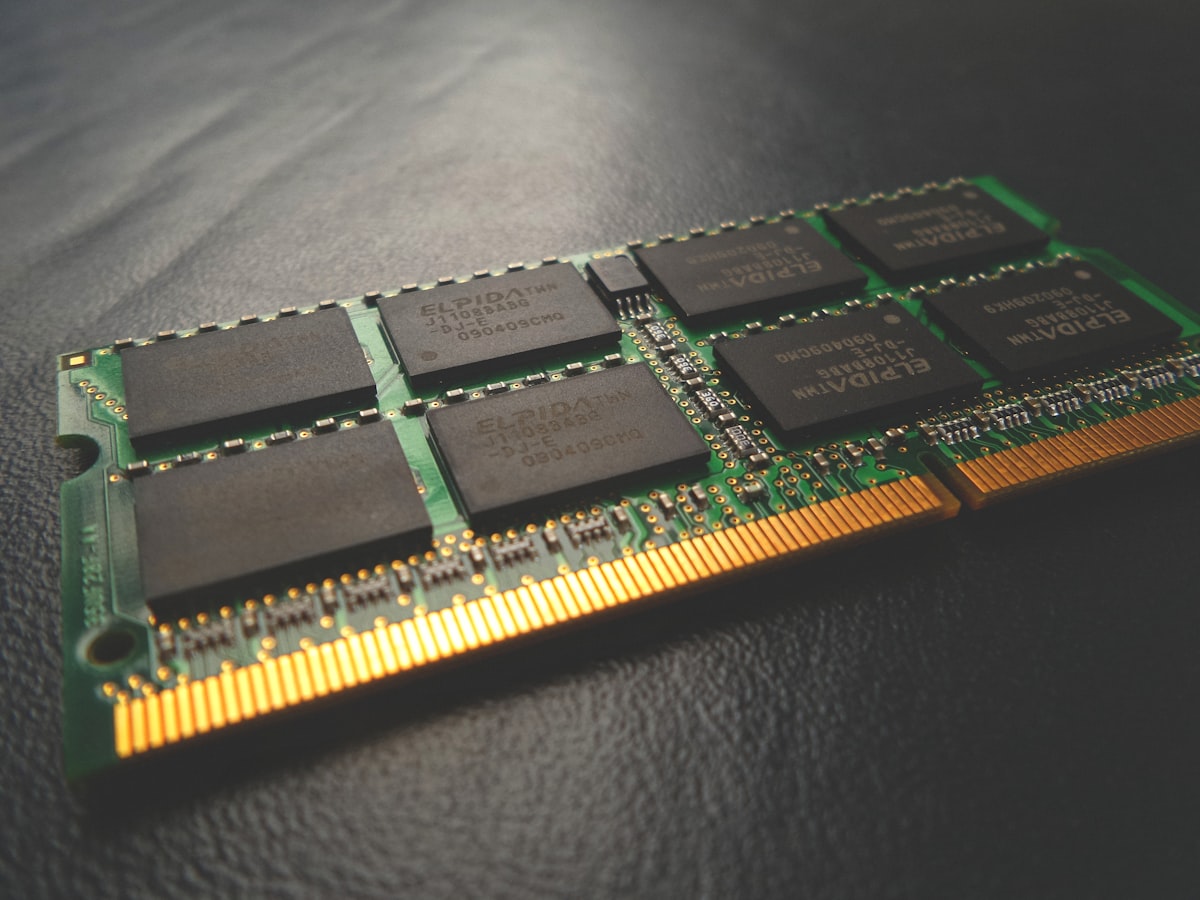
That includes the memory powering artificial intelligence, the fuel keeping the economy moving, a familiar retailer staging a comeback, and a small pharmaceutical company delivering explosive growth.
These four stocks have very different businesses, but they share something important: Each earns a Zen Rating of A (Strong Buy), a class of stocks that has historically outperformed the S&P by nearly 3 to 1. This puts them among the highest-rated stocks in WallStreetZen's quantitative model.
And with earnings announcements, seasonal demand, and other catalysts arriving in November, all four deserve a closer look.
1. Micron Technology (MU): A Cheap Way to Play the AI Boom
Artificial intelligence needs more than powerful processors. It also requires enormous amounts of high-performance memory to keep those processors running efficiently.
That's where Micron Technology (MU) comes in.
Micron manufactures high-bandwidth memory used alongside advanced chips in AI data centers. And with demand surging, the company has already sold out its high-bandwidth memory supply for the year ahead.
There's also an important catalyst on the calendar.
Nvidia is scheduled to report earnings on November 19. As a major buyer of high-bandwidth memory, Nvidia's results and outlook could influence sentiment across the memory industry, including Micron.
But Micron's investment case extends well beyond one earnings announcement.
Wall Street analysts expect the company's revenue to grow approximately 18% in the year ahead, while earnings are projected to climb roughly 55%. That's more than one and a half times the expected earnings growth rate of the broader semiconductor industry.
Despite that outlook, Micron trades at a forward price-to-earnings ratio of approximately 5.
Its PEG ratio, which measures valuation relative to expected earnings growth, sits near just 0.21. For comparison, the average stock trades around 1.5.
That suggests Micron remains attractively valued relative to its expected growth, even after its recent share-price gains.
The company has also delivered 14 consecutive earnings beats, demonstrating its ability to exceed Wall Street's expectations.
Analyst sentiment is overwhelmingly bullish. Of the 24 analysts covering Micron, 16 rate it Strong Buy and another seven rate it Buy. Their average price targets imply approximately 80% upside over the next year, based on estimates available at the time of this analysis.
What do the Zen Ratings say?
Micron earns a Zen Rating of A (Strong Buy), placing it in the top 1% of more than 4,600 stocks tracked by WallStreetZen.
Its strongest Component Grades are particularly encouraging:
- Value: Top 2%
- Financials: Top 2%
- Growth: Top 8%
- Momentum: Top 11%
- Sentiment: Top 21%
The combination of exceptional financial strength, strong expected growth, and attractive valuation makes Micron stand out.
Bottom line: Micron offers exposure to the AI infrastructure boom at a remarkably low growth-adjusted valuation. With Nvidia's upcoming earnings potentially providing another catalyst, it is one of November's more compelling semiconductor opportunities.
Now, this next one is a serious cash machine that is entering its seasonal sweet spot …
2. Valero Energy (VLO): A Cash Machine Entering a Seasonal Sweet Spot
The economy doesn't run on chips alone. It also runs on gasoline, diesel, and jet fuel.
That's the business of Valero Energy (VLO), one of the world's largest independent oil refiners.
Valero operates an extensive network of refineries, including major facilities along the Gulf Coast that benefit from access to competitively priced crude oil. The company has also expanded into renewable diesel.
And November could be an especially interesting time to own shares.
Refiners earn money from the difference between the price they pay for crude oil and the price they receive for refined products. That difference is known as the refining margin, or crack spread.
During the transition from fall to winter, several forces can support those margins.
Refineries often undergo seasonal maintenance, which can temporarily restrict fuel supply. At the same time, colder weather increases demand for heating oil and diesel.
When inventories are low, that combination can create favorable conditions for refiners.
Valero is already demonstrating the benefits of strong operating conditions.
The company reported earnings on October 22 and comfortably exceeded expectations, supported by stronger refining margins.
That marked its 22nd consecutive earnings beat, representing more than five years of consistently outperforming analysts' quarterly forecasts.
Valero has also been returning substantial cash to shareholders through dividends and aggressive share repurchases.
Despite its profitability, the stock trades at a forward P/E ratio of approximately 10, according to the valuation cited in this analysis.
Wall Street remains constructive on the shares, with a consensus Buy recommendation. Justin Jenkins of Raymond James, ranked among the top 1% of analysts, carries a Strong Buy rating.
What do the Zen Ratings say?
Valero earns a Zen Rating of A (Strong Buy), placing it in the top 1% of stocks tracked by WallStreetZen.
Its strongest Component Grades include:
- Growth: Top 1%
- Momentum: Top 1%
- Artificial Intelligence Factor: Top 1%
- Financials: Top 3%
Its Value, Sentiment, and Safety grades also rank around the top quarter of the market.
The Artificial Intelligence Factor measures a stock's potential future performance, rather than its exposure to the AI industry.
Taken together, these grades suggest a financially strong business with favorable growth prospects and positive price momentum.
There is one major risk: Refining profitability depends heavily on the spread between crude oil and finished fuel prices. If crude prices spike or fuel demand weakens, margins can contract quickly.
And although seasonal conditions can support refining margins, they don't guarantee higher profits every winter.
Bottom line: Valero combines strong cash generation, a history of earnings beats, shareholder returns, and favorable momentum. If refining margins remain elevated into winter, the company could have additional room to run.
3. Target (TGT): A Retail Comeback Ahead of the Holidays
After a difficult stretch, Target (TGT) is beginning to show signs of a meaningful turnaround.
The retail giant has struggled with sluggish sales and shifting consumer preferences, but new leadership has been working to get the business back on track.
That includes improving inventory management, sharpening merchandising, and refocusing on the products and exclusive brands that have historically attracted Target shoppers.
And the timing of that turnaround could prove important.
Target is heading into the holiday shopping season, traditionally the most consequential period of the year for retailers.
The company is scheduled to report earnings on November 18, giving investors another opportunity to evaluate the progress of its turnaround and management's expectations for holiday demand.
Target has also been emphasizing affordability, cutting prices across thousands of products to attract budget-conscious consumers.
There is already evidence that its efforts are gaining traction.
The company has delivered five consecutive earnings beats, including a particularly strong most recent quarter.
Target also offers an appealing income component.
The company is a Dividend King, having increased its annual dividend for more than 50 consecutive years.
Its dividend yield is approximately 3%, roughly twice the industry average, while its payout ratio stands around 47%.
That suggests the dividend remains well supported by earnings, provided profitability holds up.
The stock's next ex-dividend date is November 10.
Analysts are also becoming more optimistic. Target carries a consensus Buy recommendation, with highly ranked analysts such as UBS's Michael Lasser expressing confidence in its upside potential.
What do the Zen Ratings say?
Target earns a Zen Rating of A (Strong Buy), ranking in the top 2% of all stocks covered by WallStreetZen.
Its Component Grades paint a balanced picture:
- Sentiment: Top 7%
- Financials: Top 9%
- Growth: Top 13%
- Momentum: Top 13%
- Value: Top 14%
Sentiment is the standout, indicating improving signals from institutional investors and other market participants.
The combination of stronger sentiment, healthy financials, and improving growth prospects supports the case that Target's recovery is gaining traction.
However, the turnaround is still in its early stages.
Consumer spending remains uneven, particularly in discretionary categories. If shoppers pull back during the holidays, Target's sales and profitability could disappoint.
Bottom line: Target offers investors a recognizable brand, a long history of dividend growth, improving fundamentals, and a potentially important holiday-season catalyst. If its turnaround continues, shares could attract renewed investor interest.
4. Eton Pharmaceuticals (ETON): Explosive Growth at a Reasonable Price
The final stock is also the fastest-growing company on the list.
Eton Pharmaceuticals (ETON) is a relatively small pharmaceutical company focused on treatments for rare diseases.
These are conditions that larger drugmakers sometimes overlook because the patient populations are comparatively small.
But for specialized companies like Eton, those markets can offer attractive opportunities.
The company has been securing FDA approvals and introducing new treatments, creating additional revenue streams as its product portfolio expands.
Because rare-disease medications often face limited competition, successful product launches can generate recurring revenue over time.
And Eton's growth outlook is exceptional.
Wall Street analysts project revenue growth of approximately 40% annually, while earnings are expected to climb roughly 90%.
That's nearly six times the anticipated earnings growth rate of its industry.
Even more interesting, the stock has recently pulled back more than 20% from its highs despite the company's strong operating momentum.
Eton is scheduled to report earnings on November 5, making the upcoming announcement a potentially important catalyst.
The company has beaten analysts' earnings estimates for three consecutive quarters, providing some encouraging evidence that its growth expectations are achievable.
What about valuation?
Eton trades at a PEG ratio of approximately 1.17, below the broader market average of around 1.5.
That means investors aren't necessarily paying an excessive growth-adjusted premium for its projected earnings expansion.
Analyst coverage is relatively limited, with just four analysts following the stock.
However, all four currently rate it Buy or Strong Buy.
The highest-ranked analyst covering Eton, from H.C. Wainwright, sits in the top 3% of Wall Street analysts and has a price target implying roughly 40% upside over the next year, based on estimates at the time of this analysis.
What do the Zen Ratings say?
Eton earns a Zen Rating of A (Strong Buy), placing it in the top 2% of stocks tracked by WallStreetZen.
Its Component Grades include:
- Growth: Top 5%
- Financials: Top 5%
- Momentum: Top 10%
- Value: Top 19%
- Sentiment: Top 25%
Growth and Financials are its strongest areas, suggesting that Eton combines rapid expansion with improving underlying business strength.
But its small size introduces meaningful risks.
Much of Eton's future depends on the commercial performance of a relatively limited portfolio of treatments. Regulatory decisions, product launches, and changes in reimbursement can also have an outsized impact on its results.
Those risks make the stock potentially more volatile than the larger companies on this list.
Bottom line: Eton offers the fastest projected earnings growth of these four picks, an attractive growth-adjusted valuation, and a near-term earnings catalyst. For investors comfortable with the additional risks of a smaller pharmaceutical company, it is an intriguing opportunity heading into November.
Final Thoughts: Four Different Ways to Invest in November's Opportunities
The stock market's next leg higher may not look like the last one.
After years of concentrated gains among the biggest technology companies, opportunities could be emerging across a much broader range of industries.
These four stocks offer distinctly different investment cases:
- Micron (MU): Exposure to accelerating AI memory demand, strong earnings growth, and an unusually low valuation.
- Valero Energy (VLO): A profitable energy refiner with powerful momentum, significant cash generation, and potentially favorable winter demand.
- Target (TGT): A recovering retail giant with a long dividend-growth history and a crucial holiday shopping season approaching.
- Eton Pharmaceuticals (ETON): A small rare-disease drugmaker with exceptional projected earnings growth and a potentially important upcoming earnings report.
All four earn a Zen Rating of A (Strong Buy), but each carries its own risks.
Memory prices can swing sharply. Refining margins are cyclical. Retail turnarounds can stall. And smaller pharmaceutical companies face significant product and regulatory uncertainty.
Still, their strong quantitative rankings, favorable operating trends, and identifiable near-term catalysts make them four stocks worth watching closely in November 2026.
What to Do Next?
Want to get in touch? Email us at news@wallstreetzen.com.
Keep Reading
See All News


Company
AboutNewsBlogStock Investing FAQPlansPrivacy PolicyTerms of ServiceCancellation & RefundsPerformanceHelp GuidesContactTwitterYouTubeNewsletterInformation is provided 'as-is' and solely for informational purposes and is not advice. WallStreetZen does not bear any responsibility for any losses or damage that may occur as a result of reliance on this data.